"Strategy Decay"
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
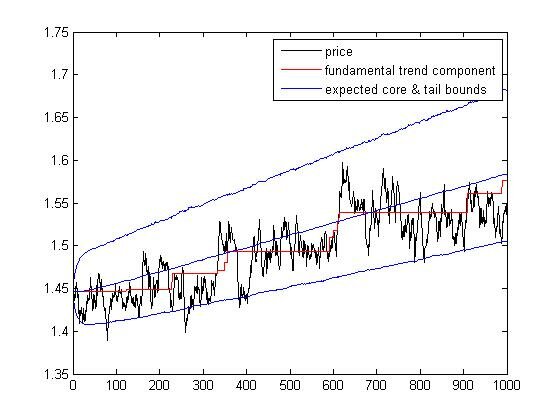
OK, I think I understand what you mean FDAX. Perhaps you are saying that if we stand any chance of tracking our drift - assuming that it is time-varying rather than constant - there must be autocorrelation in the process that describes the evolution of the drift (i.e., it follows an AR process or something). In order for us to build a better drift tracking system we need autocorrelation in the drift process. Is that closer to what you mean?
...WARNING: I am an optimal f'er
-
FDAXHunter

- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
Yes. It's just semantics, really. Point is, a line moving from the bottom left to the top right (in a reasonably manner, no singular jumps or nonsense like that) will exhibit significant autocorrelation on some level or another. Because ultimately: highs follow highs.
Now this discussion has gone a bit of track, for which I apologize.
Now this discussion has gone a bit of track, for which I apologize.
The Figs Protocol.
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
-
SubZero
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
DGN2, earlier you mentioned that the speed of decay is usually faster for high frequency strategies. Can you elaborate on that? Intuitively, I don't see why this should be.
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
Here is my take SubZero...
In my experience it is difficult to get a truly high frequency system to perform well in a broad set of market conditions (i.e., high frequency systems are typically less robust to changes in market characteristics). This isn't always true, but it is often true. For now, let’s exclude super high frequency systems where your objective is to earn the spread. These systems are very hard to backtest and the process for systematically setting performance expectations is likely different from lower frequency trading applications. I have no real experience with the super high frequency stuff so I cannot comment intelligently. I do have some experience with trading strategies that hold positions from minutes to hours though (although this experience is limited to spot FX and – to a lesser extent – futures).
If you are holding trades from minutes to hours, your performance is likely to be very sensitive to the trends at longer time scales. If you are trying to capitalize on daily/weekly seasonality or mean reversion, then sudden changes at larger scales can have a very large impact on your P&L. Usually you can do sensitivity analysis to determine how changes in market characteristics impact your system performance, but the higher frequency you trade, the more complex your model of the underlying needs to be in order to get sensible expectations out of your sensitivity analysis. The complexity of creating an underlying process model that replicates the empirical stylized facts at high frequency is more difficult than at a lower frequency. Another way you could say this is that it isn’t impossible, but it is much more difficult to distill out exactly what a high frequency system is capturing in a time series. That makes it more difficult to determine the operational domain of your strategy. You can resort to block bootstrapping to get a feel for the statistical significance of your results, etc… but you need a way to create conditions where the thing you capture is present in the time series to a lesser or greater extent. This is difficult to do if you don’t know why your model works. If you can’t specify the form of mean-reversion for instance, how can you perturb it and see what happens?
I always figured that high frequency models would be more robust because you have more trades and that somehow seems more statistically significant, but if you decompose the time series into time scales and look at the stationarity of each time scale you will see that changes in the longer time scales are unpredictable. You are exposed to those changes because mean-reversion trades scalp around these larger moves. If the larger moves are unstable, then the scalping will be unstable. That is where trend following comes in and in my opinion that is why you need a view on direction to make a real market.
Does that clarify anything?
In my experience it is difficult to get a truly high frequency system to perform well in a broad set of market conditions (i.e., high frequency systems are typically less robust to changes in market characteristics). This isn't always true, but it is often true. For now, let’s exclude super high frequency systems where your objective is to earn the spread. These systems are very hard to backtest and the process for systematically setting performance expectations is likely different from lower frequency trading applications. I have no real experience with the super high frequency stuff so I cannot comment intelligently. I do have some experience with trading strategies that hold positions from minutes to hours though (although this experience is limited to spot FX and – to a lesser extent – futures).
If you are holding trades from minutes to hours, your performance is likely to be very sensitive to the trends at longer time scales. If you are trying to capitalize on daily/weekly seasonality or mean reversion, then sudden changes at larger scales can have a very large impact on your P&L. Usually you can do sensitivity analysis to determine how changes in market characteristics impact your system performance, but the higher frequency you trade, the more complex your model of the underlying needs to be in order to get sensible expectations out of your sensitivity analysis. The complexity of creating an underlying process model that replicates the empirical stylized facts at high frequency is more difficult than at a lower frequency. Another way you could say this is that it isn’t impossible, but it is much more difficult to distill out exactly what a high frequency system is capturing in a time series. That makes it more difficult to determine the operational domain of your strategy. You can resort to block bootstrapping to get a feel for the statistical significance of your results, etc… but you need a way to create conditions where the thing you capture is present in the time series to a lesser or greater extent. This is difficult to do if you don’t know why your model works. If you can’t specify the form of mean-reversion for instance, how can you perturb it and see what happens?
I always figured that high frequency models would be more robust because you have more trades and that somehow seems more statistically significant, but if you decompose the time series into time scales and look at the stationarity of each time scale you will see that changes in the longer time scales are unpredictable. You are exposed to those changes because mean-reversion trades scalp around these larger moves. If the larger moves are unstable, then the scalping will be unstable. That is where trend following comes in and in my opinion that is why you need a view on direction to make a real market.
Does that clarify anything?
...WARNING: I am an optimal f'er
-
SubZero
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
DGN2, thanks for the explanation.
So, if I understand you correctly, you are essentially saying that the higher frequency strategies are dependent upon the conditions at lower frequencies (longer time frames).
Ok, let's go with that for a minute...
Let's say I run a strategy (call it "X") at multiple time frames (5min, 30min, daily, and weekly). Based on your theory, I should be able to predict the decline in performance (decay) of X at the 5min level by watching the decline in performance (decay) at the 30min level. I should also be able to predict the decay of X at the 30min level by watching the decay at the daily level and so on.
Would you agree? Or did I misunderstand you?
So, if I understand you correctly, you are essentially saying that the higher frequency strategies are dependent upon the conditions at lower frequencies (longer time frames).
Ok, let's go with that for a minute...
Let's say I run a strategy (call it "X") at multiple time frames (5min, 30min, daily, and weekly). Based on your theory, I should be able to predict the decline in performance (decay) of X at the 5min level by watching the decline in performance (decay) at the 30min level. I should also be able to predict the decay of X at the 30min level by watching the decay at the daily level and so on.
Would you agree? Or did I misunderstand you?
-
SubZero
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
I just thought of another way to ask my question:
Let's say I'm running strategy "X" on both a 30min time frame and a daily time frame. Let's also assume that X on a 30 minute time frame goes into a drawdown but on a daily time frame X is performing normally. In your opinion, is it reasonable to use the performance on a daily time frame to help differentiate between a drawdown and a true strategy decay (erosion) on the 30 minute time frame?
Let's say I'm running strategy "X" on both a 30min time frame and a daily time frame. Let's also assume that X on a 30 minute time frame goes into a drawdown but on a daily time frame X is performing normally. In your opinion, is it reasonable to use the performance on a daily time frame to help differentiate between a drawdown and a true strategy decay (erosion) on the 30 minute time frame?
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
I think that this will depend a lot on the strategy, but I definitely think that decomposing the performance by time scale can help you distinguish between drawdown, parameter drift, and strategy decay, particularly in the case of counter-trend trading. Mean-reversion is more or less about scaling. If scaling relationships change enough, then your strategy will decay. But once again, if you don't have a model of the mean-reversion then you can't really design something to determine the impact of parameter changes on your expectation. You can't evaluate drawdowns without an expectation. You can track the optimal parameter and if there are no parameter settings where you can perform I would say that the market characteristic you are trying to capture is not present in the asset you are trading. That doesn't mean that it won't come back but it does mean you are not going to be consistent while it is gone.
...WARNING: I am an optimal f'er
-
liquidity peddler
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
dgn2,
If I follow you, the practical solution is to wait for recent backtests of semi-hi-freq strategies to start showing strong profitability and some promise of statistical significance before turning them on.
Then one hopes that one is at the beginning of a friendly regime similar to those identified in longer backtests.
The amount of time you spend waiting and collecting positive results of course is the loss of efficiency in mining the friendly regime, but that has to be weighed against the realizable return on capital from blindly operating at all times.
If I follow you, the practical solution is to wait for recent backtests of semi-hi-freq strategies to start showing strong profitability and some promise of statistical significance before turning them on.
Then one hopes that one is at the beginning of a friendly regime similar to those identified in longer backtests.
The amount of time you spend waiting and collecting positive results of course is the loss of efficiency in mining the friendly regime, but that has to be weighed against the realizable return on capital from blindly operating at all times.
-
liquidity peddler
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
"Strategy Decay"
Just wanted to add that it seems to me (and I hope to be corrected) that a great deal of experience based intuition is an inevitable supplement to the small sample statistics we are talking about here.