Google search appears short on Global Macro Frameworks. Here is one:
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150311.pdf
Does anybody have one to share?
Global Carry, Yen and Dollar are irrefragable drivers of Global Macro. As we explain
equities and bonds are just derivatives of these factors.
SPX = long global carry + short yen + short dollar
US 10y Note = long global carry + long yen
Global Macro Framework
-
alexandergir
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
Say last two days US equties sell of is purely driven by weekness in global carry and strength in yen factor which actually compensate each other in US Bonds so not much action there.
That is very different from the first three weeks of March when selloff and recovery in US equities was just a function of the dollar factor.
That is very different from the first three weeks of March when selloff and recovery in US equities was just a function of the dollar factor.
-
alexandergir
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
Very Timely Seminal Research From BIS!
Global Asset Allocation Shifts
A couple of days ago BIS (Bank of International Settlements) released a seminal research piece “Global Asset Allocation Shifts” in which authors explain that weekly institutional and retail portfolio reallocations (not just fund flows) of U.S. investors are 90% driven by two factors easily identified as Yen (Risk On/Off) and Dollar factors hence reaffirming our Global Macro Framework. They also explore systematic predictability of these factors in great details.
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150326.pdf
https://www.bis.org/publ/work497.htm
Global Asset Allocation Shifts
A couple of days ago BIS (Bank of International Settlements) released a seminal research piece “Global Asset Allocation Shifts” in which authors explain that weekly institutional and retail portfolio reallocations (not just fund flows) of U.S. investors are 90% driven by two factors easily identified as Yen (Risk On/Off) and Dollar factors hence reaffirming our Global Macro Framework. They also explore systematic predictability of these factors in great details.
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150326.pdf
https://www.bis.org/publ/work497.htm
-
alexandergir
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
Seriously?
Global Carry keeps pushing through the roof. For a long term investor or risk parity portfolio fortune maker generating 1.5 sharpe using such a simple portfolio (10y+spx) which was not even touched or rebalanced for over 6y now...
Meanwhile Recession/credit blowout headline stories are breaking the news on ZH:
http://www.zerohedge.com/news/2015-04-13/unseen-recession-shocker-crushing-economy-revealed-credit-rejections-soar-most-ever
I mean it will really end in tears for risk parity, carry holders and whatever is close to it like 60/40 which is everywhere... the disconect is getting mind blowing.
Apologies for the rant.
Global Carry keeps pushing through the roof. For a long term investor or risk parity portfolio fortune maker generating 1.5 sharpe using such a simple portfolio (10y+spx) which was not even touched or rebalanced for over 6y now...
Meanwhile Recession/credit blowout headline stories are breaking the news on ZH:
http://www.zerohedge.com/news/2015-04-13/unseen-recession-shocker-crushing-economy-revealed-credit-rejections-soar-most-ever
I mean it will really end in tears for risk parity, carry holders and whatever is close to it like 60/40 which is everywhere... the disconect is getting mind blowing.
Apologies for the rant.
-
tbretagn

- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
How's risk parity doing alex?
Et meme si ce n'est pas vrai, il faut croire en l'histoire ancienne
-
NeroTulip
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
@tbretagn: sounds harsh.
To alex's credit, he stated that a simple risk parity portfolio has a 5y Sharpe of ~1.5, which is more of a fact than an opinion, and added "it will end in tears", which is not exactly an endorsement of the strategy.
I tend to agree that we could see an unwind of the last 6 years' yield grab, which means that anything with a yield could take a hit: equities, bonds, credit, carry, etc... could all go out of the window at the same time.
@alex: happy to hear more thoughts
To alex's credit, he stated that a simple risk parity portfolio has a 5y Sharpe of ~1.5, which is more of a fact than an opinion, and added "it will end in tears", which is not exactly an endorsement of the strategy.
I tend to agree that we could see an unwind of the last 6 years' yield grab, which means that anything with a yield could take a hit: equities, bonds, credit, carry, etc... could all go out of the window at the same time.
@alex: happy to hear more thoughts
Inflatable trader
-
tbretagn
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
Sorry didn't mean to sound harsh, but agreed it does. Actually am very curious about it and I very much like Alex's reports.
Think part of the problem is a lack of liquidity and fast money staying on the sideline. Am interested in the risk parity view because if they start to move then things will get ugly (for example credit spreads haven't really moved lately - for some obvious reasons but nonetheless).
So alex, updates are welcome
Think part of the problem is a lack of liquidity and fast money staying on the sideline. Am interested in the risk parity view because if they start to move then things will get ugly (for example credit spreads haven't really moved lately - for some obvious reasons but nonetheless).
So alex, updates are welcome
Et meme si ce n'est pas vrai, il faut croire en l'histoire ancienne
-
alexandergir
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
updates:
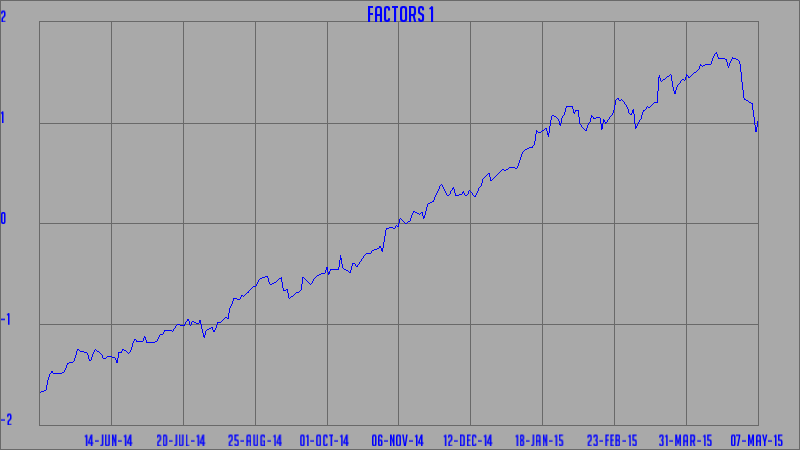
lots of tears over last two weeks which were really all about "global carry" unwind:
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150429.pdf
as i put it two weeks ago if Bunds go so will global carry
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150421.pdf
and it did, largest correction since Taper Tantrum actually, and it is behind most of the liquid assets reversals which created lots of pain for momentum folks too. Desperate recovery now:
[img]/User%20Files/3871/chart_2_1.png[/img]
lots of tears over last two weeks which were really all about "global carry" unwind:
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150429.pdf
as i put it two weeks ago if Bunds go so will global carry
http://www.dynamikacapital.com/public/pdfs/DynamikaCommentary20150421.pdf
and it did, largest correction since Taper Tantrum actually, and it is behind most of the liquid assets reversals which created lots of pain for momentum folks too. Desperate recovery now:
[img]/User%20Files/3871/chart_2_1.png[/img]
You do not have the required permissions to view the files attached to this post.
-
misc2014
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
A really interesting thread for me... I invest on a 5 year horizon optimised for monthly yield, long only, indexes only: corp bond (GBP,EUR), EM bond (USD,LOCAL), gov bond (GBP), high div equity (e.g. IAPD.L), REIT (USD/GBP). Skewed heavily toward bonds, targeting a 4.5% annual return. Have about 35% of the portfolio in cash, waiting for a catastrophe.
Pretty much everything has gone south at the same time... From a retail investors perspective, how would you suggest positioning over the next 2 years?
Pretty much everything has gone south at the same time... From a retail investors perspective, how would you suggest positioning over the next 2 years?
-
tbretagn
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Global Macro Framework
Yes I believe risk parity worked as a pure QE trade. Though the ECB QE could continue the trend, it will be much much harder. Personally I think we are in the same conundrum as early 2009, where market was under heavy pressure from over leniency and exaggerated positions.
@misc2014: imo credit is very dangerous given lack of warehousing from banks. Govies are not entering a bear market, but sharpe is too low. I'd stick with equities, after the collapse we could see coming in the next few months (or invest in european equities if it makes sense).
@misc2014: imo credit is very dangerous given lack of warehousing from banks. Govies are not entering a bear market, but sharpe is too low. I'd stick with equities, after the collapse we could see coming in the next few months (or invest in european equities if it makes sense).
Et meme si ce n'est pas vrai, il faut croire en l'histoire ancienne