filthy,
It would be good to see a section on the skew - it's sources, ways to measure, types of trades, sources of p&l etc. I would also talk about the thought process to come up with new trade ideas.
doobs,
If you promise not to share it with other "market participants", I can send you a few bits of R code on the term structure and ways to think about it. Personally, I think there is are more risk-premium mis-pricing in the term structure then in the strike space and there is a lot of money to be made there.
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
-
Strange

- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
--That word, you keep using that word! I don't think it means what you think it means
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
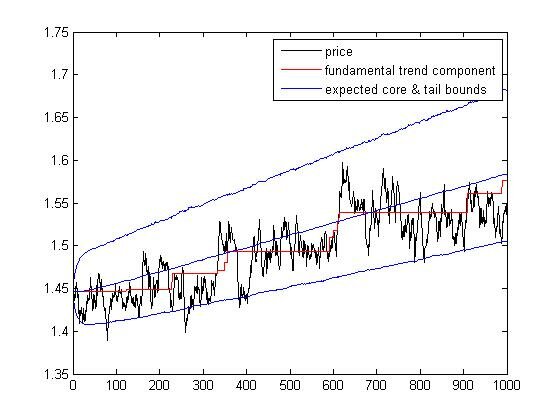
Filthy, you mentioned you were thinking about adding more stuff on mean reversion. I would love to see something about kelly-like bet sizing on a process that reverts around a trend.
Here are a few pictures of realizations from the sort of process I mean:
[img]/User%20Files/41/driftRegimeChangeOUProcess.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v2.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v3.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v4.jpg[/img]
This is just an OU process where the drift has jumps that arrive according to a gamma process (reduces to Poisson process under certain parameter settings). Under some parameter settings the paths look a lot like the uncertain drift parameter case.
Here are a few pictures of realizations from the sort of process I mean:
[img]/User%20Files/41/driftRegimeChangeOUProcess.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v2.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v3.jpg[/img]
[img]/User%20Files/41/driftRegimeChangeOUProcess_v4.jpg[/img]
This is just an OU process where the drift has jumps that arrive according to a gamma process (reduces to Poisson process under certain parameter settings). Under some parameter settings the paths look a lot like the uncertain drift parameter case.
You do not have the required permissions to view the files attached to this post.
...WARNING: I am an optimal f'er
-
filthy
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
dgn,
we talked about that right? was that the stuff i said i thought i knew how to do?
we talked about that right? was that the stuff i said i thought i knew how to do?
"Game's the same, just got more fierce"
-
dgn2
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
We did talk about that, but I don't remember whether or not you thought you knew what to do. I think we mostly just talked about how this is what is required to trade mean reversion in the real world. I have some ideas, but not a full solution (and nothing elegant)
...WARNING: I am an optimal f'er
-
doobs

- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
Strange, I promise to not share with other "market participants". Email in profile.
-
TonyC
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
Strange Wrote:
> If you promise not to share it with other "market participants", I can send you a few
> bits of R code on the term structure and ways to think about it. Personally, I think
> there is are more risk-premium mis-pricing in the term structure then in the strike
> space and there is a lot of money to be made there.
it's been a long time since i traded fixed income, but in my experience the co-variance matrix of forward points on the yield curve is much more stable over time than the co-variance matrix of just about any commodity future curve . . .
. . . do you think the above observation would make your R analysis better or worse if applied to commodities? Give me a holler, you've got my contact info
> If you promise not to share it with other "market participants", I can send you a few
> bits of R code on the term structure and ways to think about it. Personally, I think
> there is are more risk-premium mis-pricing in the term structure then in the strike
> space and there is a lot of money to be made there.
it's been a long time since i traded fixed income, but in my experience the co-variance matrix of forward points on the yield curve is much more stable over time than the co-variance matrix of just about any commodity future curve . . .
. . . do you think the above observation would make your R analysis better or worse if applied to commodities? Give me a holler, you've got my contact info
flaneur/boulevardier/remittance man/energy trader
-
doobs
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
Tony, the Cov-matrix of most commodity vol structures are super hared to guesstimate - do you not agree? Have you tried to tackle that in any meaningful way?
-
TonyC
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
define meaningful? Confused
as a practical matter i tend to use some very simple Bayesian seasonality stuff . . . but you never know what one might discover by revisiting stuff (like 3 factor models) that one dismissed many years ago . . . maybe Strange's stuff might be applicable to commodities
as a practical matter i tend to use some very simple Bayesian seasonality stuff . . . but you never know what one might discover by revisiting stuff (like 3 factor models) that one dismissed many years ago . . . maybe Strange's stuff might be applicable to commodities
flaneur/boulevardier/remittance man/energy trader
-
Strange
- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
Tony, it's a volatility term structure analysis, as in "buy 1m options, sell 3m options". Personally, I found that commodities vol term structure gives you the most opportunities, as, in additional to usual risk premiums, there are a lot of other factors. We should talk in person about it, when you have a little time. Plus, I still owe you a drink.
--That word, you keep using that word! I don't think it means what you think it means
-
HyperVolatility

- Posts: 0
- Joined: Thu Jan 01, 2004 12:00 am
Volatility Trading + CDROM by Euan Sinclair, Ph.D.
Strange: "It would be good to see a section on the skew - it's sources, ways to measure, types of trades, sources of p&l etc. I would also talk about the thought process to come up with new trade ideas. "
I totally agree with Strange. A section on skew and how to trade it would be EXTREMELY interesting.
If I can add something I would suggest "trading the term structure" (as other people suggested) and "ways to measure the volatility in terms of speed rather than magnitude".
Last but not least, what about an inter-market volatility trade analysis using positively correlated assets which show a fairly good covariance?(I know I'm asking too much; sorry).Thanks Filthy. I can't wait to read it.
@ Strange: would it be possible for you to send me the R code (email is in the profile)?Please!! I would really appreciate that and I won't spread it around.
Also, if you guys happen to be in London I would love to join the conversation about volatility.
thank you chaps
I totally agree with Strange. A section on skew and how to trade it would be EXTREMELY interesting.
If I can add something I would suggest "trading the term structure" (as other people suggested) and "ways to measure the volatility in terms of speed rather than magnitude".
Last but not least, what about an inter-market volatility trade analysis using positively correlated assets which show a fairly good covariance?(I know I'm asking too much; sorry).Thanks Filthy. I can't wait to read it.
@ Strange: would it be possible for you to send me the R code (email is in the profile)?Please!! I would really appreciate that and I won't spread it around.
Also, if you guys happen to be in London I would love to join the conversation about volatility.
thank you chaps
WWW.HYPERVOLATILITY.COM